Insights

Insights · Page 6

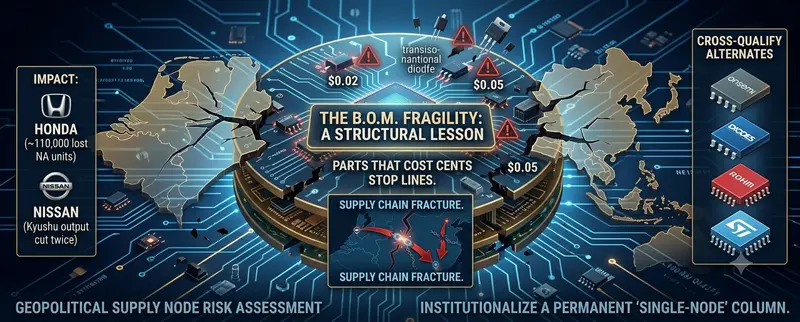
The Nexperia Discrete Disruption Is a Structural Lesson, Not a One-Off: What OEM and EMS Buyers Should Institutionalize Before the Next Single-Node Failure

June 10, 2026 · By WingCore Editorial

The Nexperia Discrete Disruption Is a Structural Lesson, Not a One-Off: What OEM and EMS Buyers Should Institutionalize Before the Next Single-Node Failure

Nexperia's supply disruption has dragged from late September 2025 into mid-2026, with some legacy parts now quoted as unavailable until July 2026 or later. The headline is automotive pain, but the deeper lesson is structural: a single geopolitically exposed assembly-and-test node can sever a billion-dollar discrete supply with no warning. This is a strategic read for OEM and EMS sourcing teams on how to harden BOMs against single-node failure.

supply-riskprocurementsupply-chain2026-q2
Read more →
Helium Becomes the Quiet Single Point of Failure in the 2026 Memory Supply Chain — A Sourcing Read for OEM and EMS Buyers

June 8, 2026 · By WingCore Editorial

Helium Becomes the Quiet Single Point of Failure in the 2026 Memory Supply Chain — A Sourcing Read for OEM and EMS Buyers

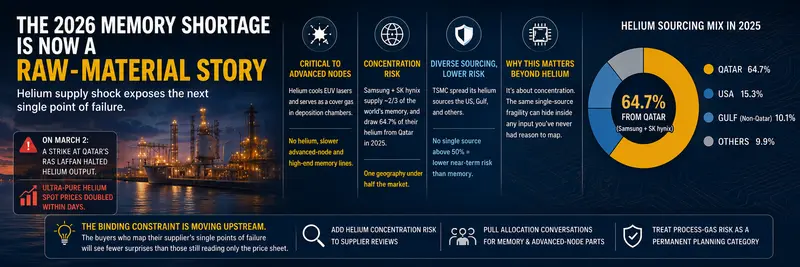
The 2026 memory squeeze has been told almost entirely as a pricing and allocation story. This week reframed it as a raw-material risk. A strike on Qatar's Ras Laffan halted helium output, doubled spot prices, and forced Korean memory fabs to ration a gas with no substitute. For OEM and EMS procurement, helium concentration risk is now a line item that deserves the same attention as wafer allocation.

supply-risksupply-chainprocurement2026-q2
Read more →
The SiC Paradox of 2026: Substrate Glut, Device Tightness, and Why the 8-Inch Transition Hands China the Leverage as AI Data Centers Go 800V

June 5, 2026 · By WingCore Editorial

The SiC Paradox of 2026: Substrate Glut, Device Tightness, and Why the 8-Inch Transition Hands China the Leverage as AI Data Centers Go 800V

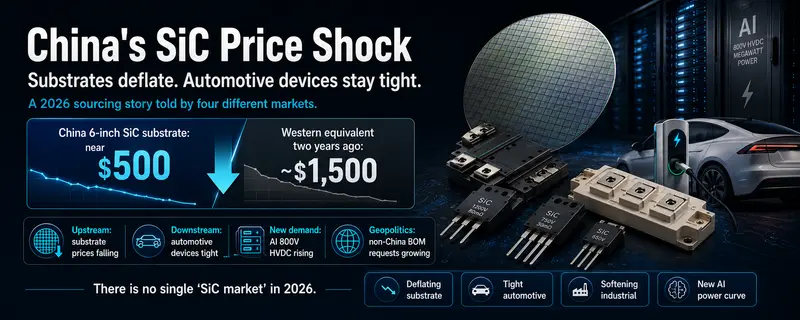
A June 4 DigiTimes exclusive describes China consolidating control of the silicon carbide supply chain as the industry pivots to 8-inch wafers. With Chinese 6-inch substrates quoting near $500 against still-constrained automotive SiC MOSFETs, and 800V HVDC AI data centers emerging as a second demand pillar, OEM and EMS sourcing teams face a market moving in two directions at once. This analysis maps the structural shift and its procurement consequences.

marketai-demandsupply-risksupply-chain
Read more →
The Other NAND Crisis: Why SLC, MLC, and Low-Density eMMC Are Disappearing Faster Than the AI Memory Boom Suggests

June 5, 2026 · By WingCore Editorial

The Other NAND Crisis: Why SLC, MLC, and Low-Density eMMC Are Disappearing Faster Than the AI Memory Boom Suggests

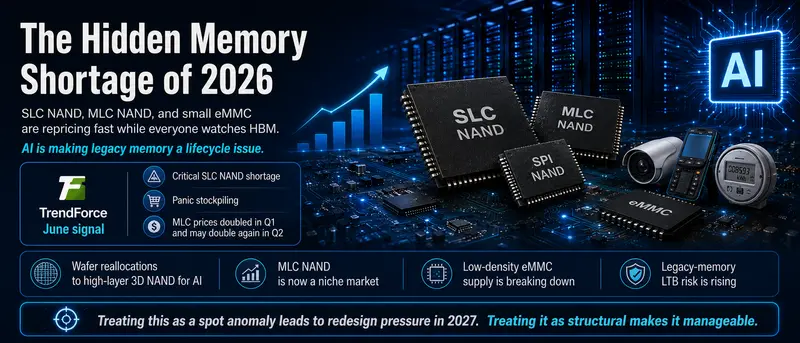
While the industry watches enterprise NAND allocation battles, a quieter crisis is unfolding at the opposite end of the density spectrum. SLC NAND shortages have triggered panic stockpiling, MLC contract prices doubled in Q1 2026 with another doubling possible in Q2, and low-density eMMC supply is breaking down as major manufacturers exit legacy nodes. This analysis examines the structural drivers and what they mean for OEM and EMS sourcing strategy.

memoryeMMCindustrialsupply-risk
Read more →
Power Semiconductors Become the Second Front of the 2026 Pricing Wave: Reading Infineon's July 1 Hike for OEM and EMS Sourcing Strategy

June 3, 2026 · By WingCore Editorial

Power Semiconductors Become the Second Front of the 2026 Pricing Wave: Reading Infineon's July 1 Hike for OEM and EMS Sourcing Strategy

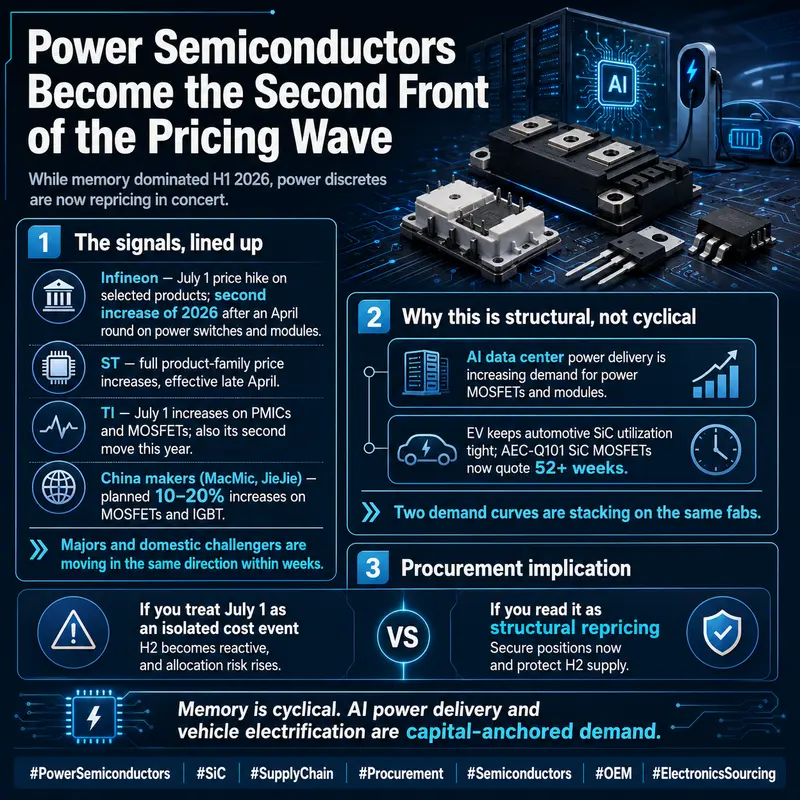
For most of the first half of 2026, the procurement conversation lived inside memory — DRAM and NAND allocation, HBM4E samples, DDR5 contract resets. Power semiconductors moved more quietly, but they are now unmistakably the second front of the pricing wave, and the fundamentals beneath them are arguably more durable than the memory cycle. This briefing reads Infineon's July 1 second hike, ST's repricing, and the 52-week SiC bottleneck as a single strategic signal for OEM and EMS buyers.

marketai-demandprocurement2026-q2
Read more →
Samsung's HBM4E Sample Lead Has Already Reshaped 2027 AI Memory Procurement — A Strategic Read for OEM and Hyperscale Buyers

June 1, 2026 · By WingCore Editorial

Samsung's HBM4E Sample Lead Has Already Reshaped 2027 AI Memory Procurement — A Strategic Read for OEM and Hyperscale Buyers

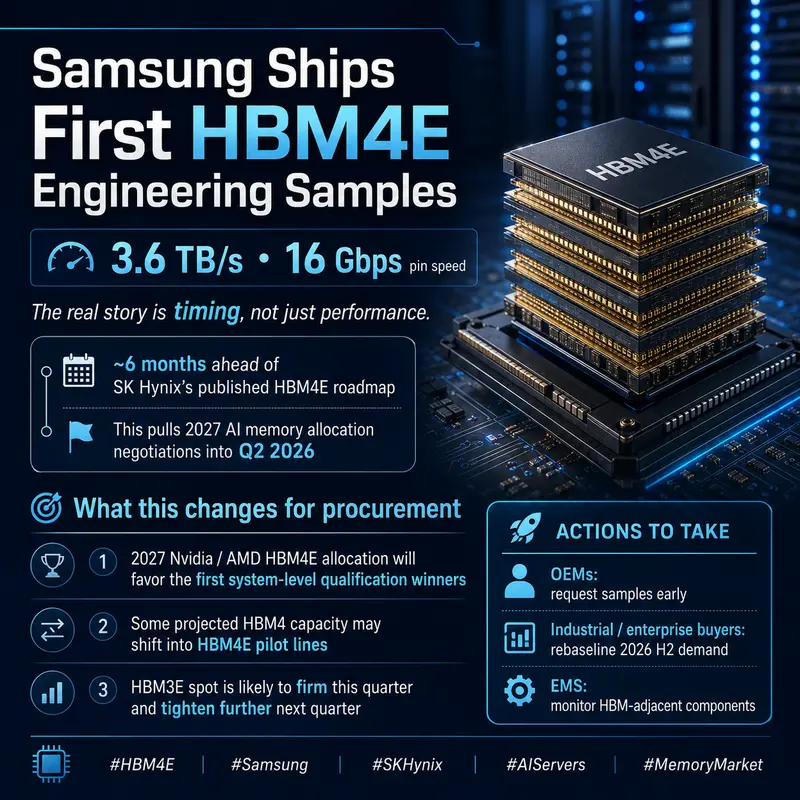
Samsung's May 30 delivery of the industry's first HBM4E engineering samples — at 3.6 TB/s and 16 Gbps pin speed — is being reported as a performance milestone. For OEM, EMS, and hyperscale procurement teams, the substantive impact is different. It pulls the 2027 HBM allocation negotiation cycle into Q2 2026, redistributes 2026 H2 HBM4 capacity assumptions, and forces buyers to revisit second-source qualification timelines that had been comfortably parked. This briefing outlines what changes and why the response window is narrower than it appears.

memoryai-demandsamsungsupply-chain
Read more →
From Pricing Cycle to Allocation Reality: How Kioxia's 2026 Sell-Out, 332-Layer QLC, and 245TB SSDs Reshape Industrial and AI Storage Procurement

May 29, 2026 · By WingCore Editorial

From Pricing Cycle to Allocation Reality: How Kioxia's 2026 Sell-Out, 332-Layer QLC, and 245TB SSDs Reshape Industrial and AI Storage Procurement

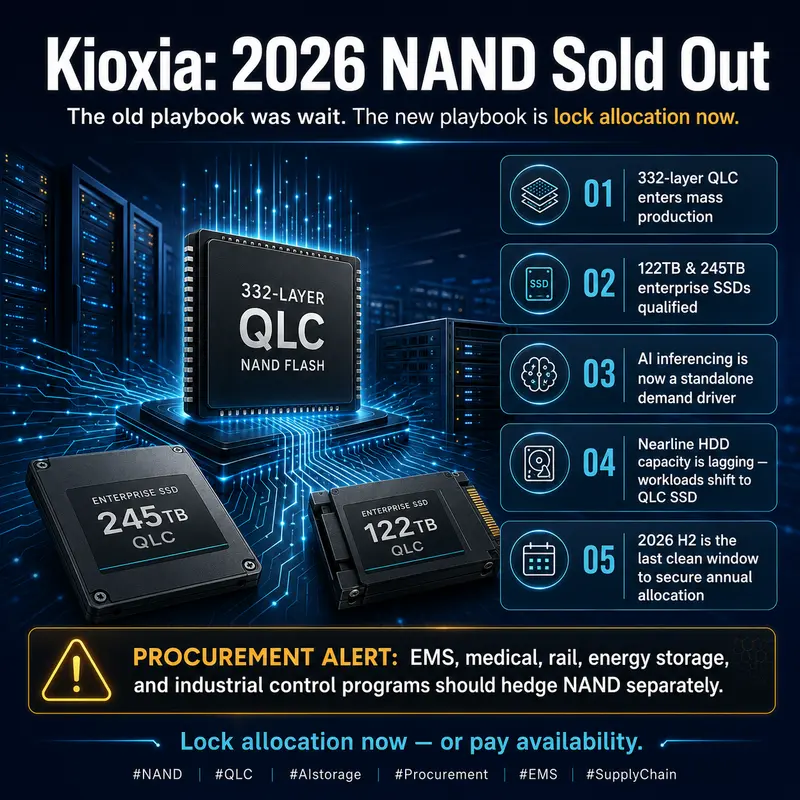
Kioxia's public acknowledgment that calendar 2026 NAND production is fully allocated is not just another supply headline. Combined with the 332-layer QLC ramp and the qualification of 122TB and 245TB enterprise SSDs, it signals a structural shift in how the storage tier will be built for AI inferencing and how nearline HDD workloads migrate to SSD. Industrial OEMs and EMS buyers should treat 2026 H2 as the last clean planning window before allocation becomes the dominant scarcity, not price.

memoryai-demandsupply-risksupply-chain
Read more →
Why the 2026 MLCC Crunch Will Outlast the AI Memory Cycle: An Industrial OEM and EMS Procurement Briefing on 1206/1210 High-Capacitance Supply

May 28, 2026 · By WingCore Editorial

Why the 2026 MLCC Crunch Will Outlast the AI Memory Cycle: An Industrial OEM and EMS Procurement Briefing on 1206/1210 High-Capacitance Supply

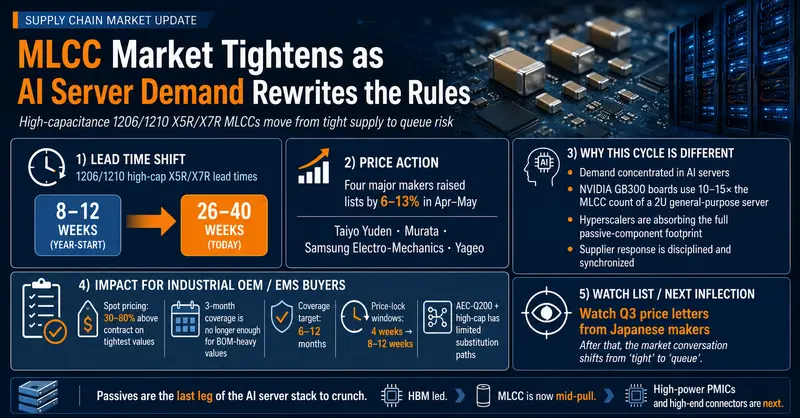
The 2026 multilayer ceramic capacitor cycle is structurally different from 2017-2018. AI server boards now consume MLCCs at 10-15x the rate of general-purpose servers, and four major makers have responded with coordinated 6-13% list increases that pushed 1206/1210 high-capacitance lead times from 8-12 weeks to 26-40 weeks. For industrial OEMs and EMS buyers, this is not a temporary spike but a multi-year repricing of an entire passive-component class. This briefing walks through what is driving the squeeze, where the substitution paths still work, and how procurement teams should restructure their MLCC sourcing posture for 2026 H2 and 2027.

marketprocurementsupply-chainai-demand
Read more →
DDR5 Pricing Resets and 2026 Allocation Lockout: What Industrial OEM and EMS Buyers Need to Reprice Now

May 27, 2026 · By WingCore Editorial

DDR5 Pricing Resets and 2026 Allocation Lockout: What Industrial OEM and EMS Buyers Need to Reprice Now

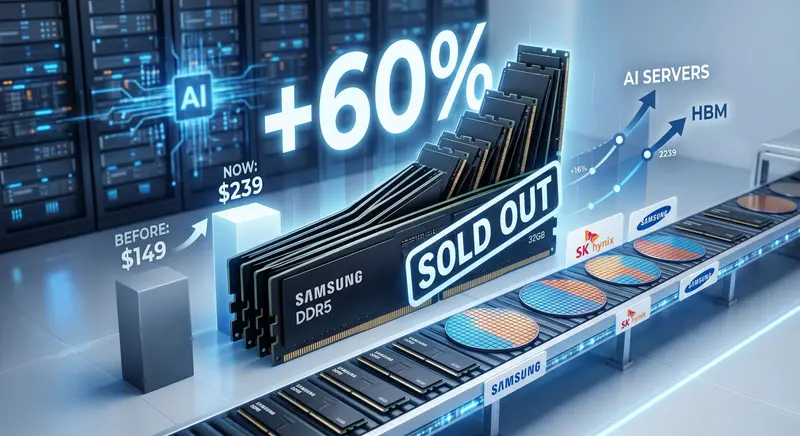
Samsung's near-60% DDR5 contract price reset and SK hynix's admission that 2026 HBM, DRAM and NAND capacity is essentially sold out mark the moment commodity memory pricing detaches from prior baselines. For industrial OEM, EMS and ODM buyers, the immediate exposure sits in DDR5, LPDDR5, eMMC and LPDDR4 — not in HBM. This is a structural reset, and the response window is the next quarter.

marketmemoryai-demandprocurement
Read more →
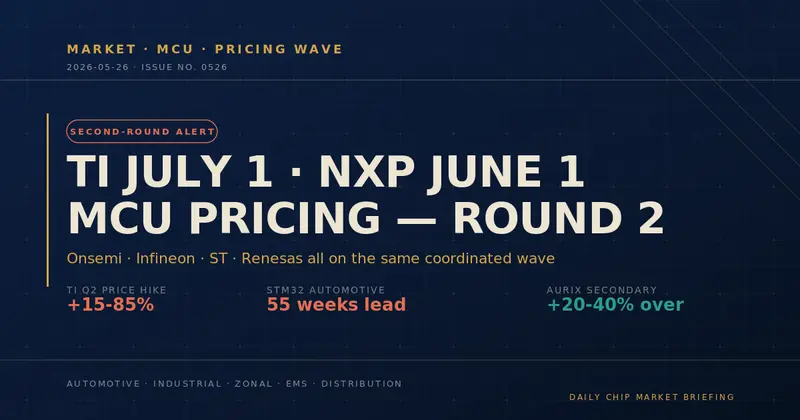
The Same-Year Second MCU Pricing Wave: What TI's July 1 And NXP's June 1 Tell Industrial And Automotive Buyers About 2026 H2

May 26, 2026 · By WingCore Editorial

The Same-Year Second MCU Pricing Wave: What TI's July 1 And NXP's June 1 Tell Industrial And Automotive Buyers About 2026 H2

TI's July 1 second-round price increase and NXP's June 1 follow-up are not isolated supplier moves. They are the clearest signal yet that legacy-process MCU pricing has moved from annual contracts to rolling cost-plus, and that industrial and automotive procurement organisations need to restructure how they plan budgets and place safety orders through 2026 H2. This is a buyer-side analysis of the pricing mechanics, the lead-time exposure, and what disciplined sourcing teams should be planning today.

marketprocurement2026-q2industrial
Read more →
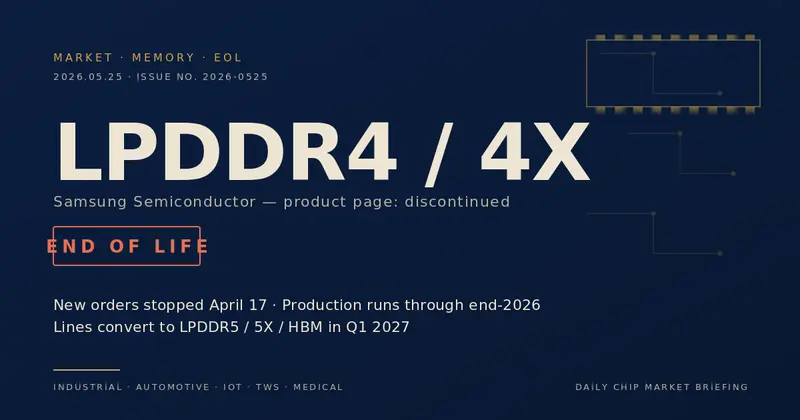
Samsung Confirms LPDDR4 and LPDDR4X End-of-Life: The Quiet Forced Migration for Industrial and Long-Lifecycle Products

May 25, 2026 · By WingCore Editorial

Samsung Confirms LPDDR4 and LPDDR4X End-of-Life: The Quiet Forced Migration for Industrial and Long-Lifecycle Products

Samsung's product pages now mark LPDDR4 and LPDDR4X as discontinued. New orders have stopped, production runs out by end-2026, and lines fully convert to LPDDR5/5X and HBM in Q1 2027. For mobile SoCs the impact is manageable. For industrial, automotive infotainment, IoT and medical devices — where product lifecycles run 5 to 15 years — this is the start of a difficult forced migration.

memoryLPDDR4samsungsupply-risk
Read more →