Insights

Insights · Page 3

Qualcomm–Amazon Custom AI Silicon Program Links Inference Compute, 1.6T Optics and Cloud EDA

September 9, 2026 · By WingCore Editorial

Qualcomm–Amazon Custom AI Silicon Program Links Inference Compute, 1.6T Optics and Cloud EDA

The multi-generation Qualcomm–Amazon program combines custom inference silicon with optical connectivity up to 1.6T. It also extends to AWS-based EDA workflows, linking deployed infrastructure with chip development. The commercial supply effect remains milestone-dependent because no device, manufacturing plan or service date has been disclosed.

ai-demandprocurementsupply-chain
Read more →
Notebook CPU Availability Improves as Memory and Processor Costs Rise to 68% of System BOM

September 7, 2026 · By WingCore Editorial

Notebook CPU Availability Improves as Memory and Processor Costs Rise to 68% of System BOM

Notebook CPU availability has improved since the second quarter, reducing production disruption risk. However, CPU, DRAM and SSD now represent 68% of mainstream notebook BOM cost, compared with about 45% in early 2025. OEM and EMS exposure is shifting from allocation risk to the timing of inventory depletion and cost pass-through.

marketmemoryprocurementsupply-chain
Read more →
Samsung's HBM5 and zHBM Roadmap Moves AI Memory Competition From Peak Bandwidth to System-Level Deliverability

September 2, 2026 · By WingCore Editorial

Samsung's HBM5 and zHBM Roadmap Moves AI Memory Competition From Peak Bandwidth to System-Level Deliverability

Samsung's September 1 roadmap sets HBM5 at roughly twice HBM4E performance and positions zHBM for an eightfold step beyond HBM5. The commercial significance lies less in the peak figures than in the expanded qualification burden across bonding, packaging, thermal control and test. OEM and EMS planning should distinguish technical targets from certified, allocable output.

memoryai-demandprocurementsamsung
Read more →
The $250 Million Diodes–ElevATE Transaction Expands ATE Analog IC Exposure Without an Immediate Supply Reset

August 31, 2026 · By WingCore Editorial

The $250 Million Diodes–ElevATE Transaction Expands ATE Analog IC Exposure Without an Immediate Supply Reset

Diodes completed its acquisition of ElevATE Semiconductor for $250 million in cash. Management expects roughly $50 million of revenue contribution in the first twelve months and immediate accretion to revenue, gross margin and earnings per share. ElevATE will continue as a product line, making continuity the disclosed near-term operating model rather than product rationalization.

marketprocurementsupply-chain
Read more →
When Export Controls Reach the Installed Base: What the MATCH Act's Servicing Clause Means for OEM and EMS Sourcing of Mature-Node Components

August 26, 2026 · By WingCore Editorial

When Export Controls Reach the Installed Base: What the MATCH Act's Servicing Clause Means for OEM and EMS Sourcing of Mature-Node Components

The MATCH Act, now being pushed back toward the Senate NDAA, would ban DUV immersion and cryogenic etch exports to China and, more consequentially, bar ASML from servicing the tools already installed there. For OEM and EMS sourcing organizations, the relevant exposure is not leading-edge logic but the mature-node output that supplies general-purpose MCUs, analog, power discretes, NOR and DDR4. With domestic DUV output at roughly five systems in 2026 against 95 imported in 2025, substitution capacity does not exist inside the relevant planning horizon.

marketprocurementsupply-risksupply-chain
Read more →
When Repricing Becomes Category-Wide: What ST's Third 2026 Increase and 52-Week Power Lead Times Mean for OEM and EMS Sourcing

August 24, 2026 · By WingCore Editorial

When Repricing Becomes Category-Wide: What ST's Third 2026 Increase and 52-Week Power Lead Times Mean for OEM and EMS Sourcing

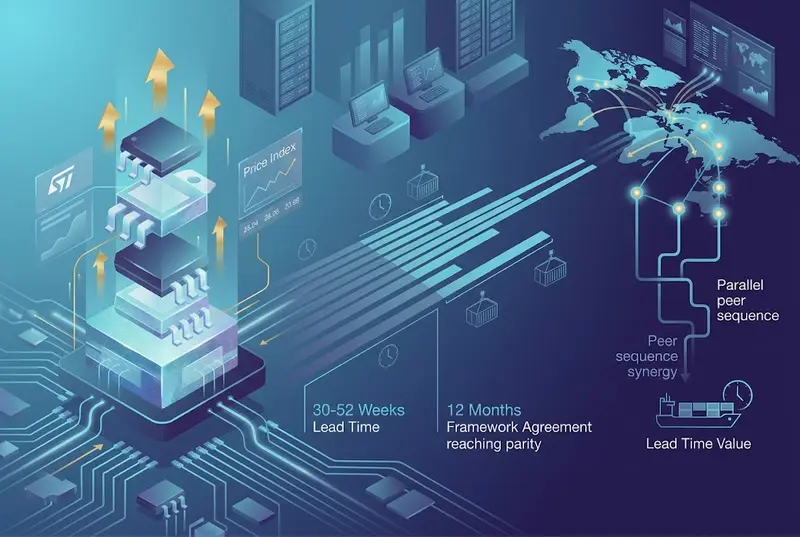
STMicroelectronics' third price increase of 2026 became effective on August 23, covering power ICs, general-purpose MCUs, NFC RF chips and power semiconductors, with automotive MCU pricing up a cumulative 15–20% and power device lead times running from 30 to 52 weeks. Read alongside comparable moves from TI, NXP, Infineon and onsemi, the event marks the point at which analog and power repricing stops being a supplier-specific negotiation and becomes a structural feature of the category. This analysis examines the cadence of the 2026 rounds, the way lead times and pricing reinforce one another, and the implications for OEM and EMS sourcing strategy through 2027.

marketprocurementindustrialsupply-risk
Read more →
When Heat Becomes the Binding Constraint: What Packaging Thermal Limits Mean for OEM and EMS Sourcing Through 2027

August 21, 2026 · By WingCore Editorial

When Heat Becomes the Binding Constraint: What Packaging Thermal Limits Mean for OEM and EMS Sourcing Through 2027

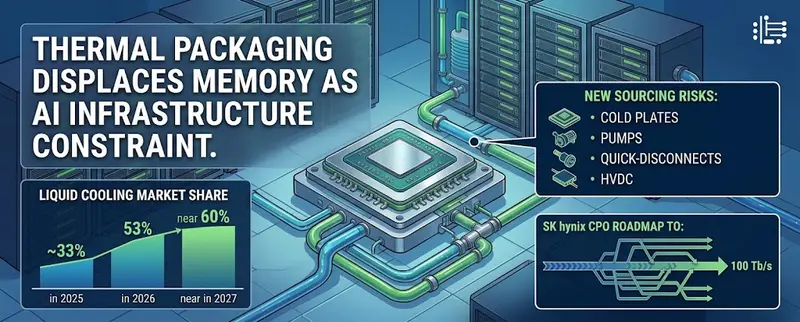
Packaging thermals have overtaken memory as the primary constraint on AI infrastructure expansion, according to researchers presenting this week. Individual AI processors now exceed 1kW TDP and rack systems draw hundreds of kilowatts, while liquid cooling penetration climbs from roughly 33% in 2025 to 53% in 2026 and near 60% in 2027. For OEM and EMS organisations, the shift relocates programme risk from semiconductor allocation into thermal and power-delivery hardware, categories that most sourcing structures were never built to track. The mitigation paths under discussion, CPO and STCO, are real but arrive on a timeline that leaves 2026 and 2027 schedules unchanged.

ai-demandsupply-chainmarketsupply-risk
Read more →
When the Price Cycle Becomes Booked Profit: What NAND's 77% Revenue Quarter Means for OEM and EMS Sourcing Strategy

August 19, 2026 · By WingCore Editorial

When the Price Cycle Becomes Booked Profit: What NAND's 77% Revenue Quarter Means for OEM and EMS Sourcing Strategy

TrendForce's Q2 2026 figures show combined revenue at the top five NAND Flash brands reaching US$68.87bn, a 77% quarter-on-quarter increase driven almost entirely by average selling prices rather than bit shipments. Micron advanced to third place on 99.2% growth and SK hynix Group recorded its highest-ever operating margin. For OEM and EMS organisations, the significance lies less in the headline figure than in what it demonstrates about supplier incentives for the remainder of the cycle. This piece examines why an ASP-led quarter forecloses the mean-reversion assumption embedded in most sourcing models, and how the arrival of YMTC's 8-plane QLC in volume changes — and does not change — the second-source calculus.

marketmemoryai-demandprocurement
Read more →
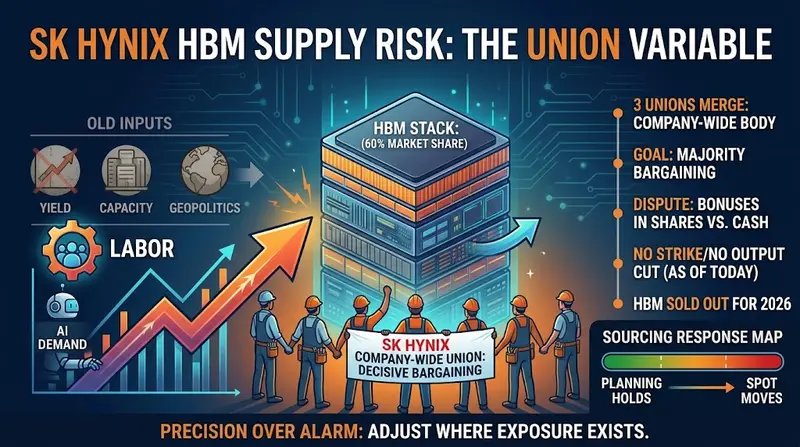
When Labor Risk Meets the Allocation Peak: What SK Hynix's Union Consolidation Signals for HBM and DDR5 Sourcing Strategy

August 17, 2026 · By WingCore Editorial

When Labor Risk Meets the Allocation Peak: What SK Hynix's Union Consolidation Signals for HBM and DDR5 Sourcing Strategy

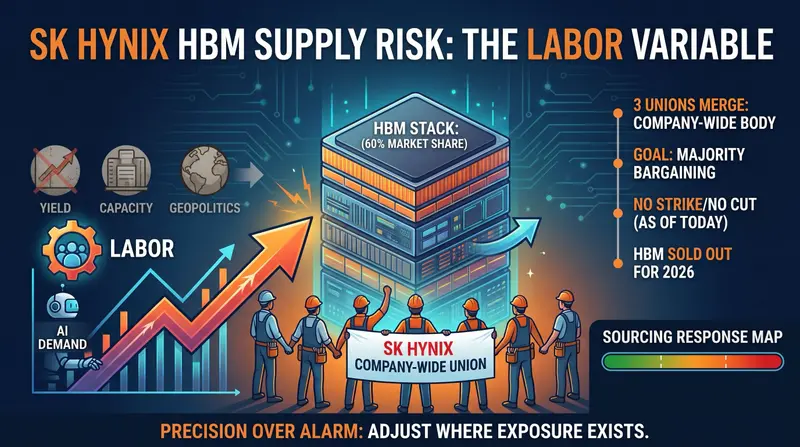
SK Hynix's Korean workforce consolidated three unions into a single company-wide body on August 13, with annual wage talks deadlocked over whether bonuses are paid in cash or shares. For OEM and EMS sourcing teams, the specifics of a Korean labor negotiation matter less than the structural read: for the first time in this cycle, the world's largest HBM supplier carries an organized labor variable, and it arrives precisely as allocation is at its tightest. This piece frames what the development does — and doesn't — change for HBM, server DDR5 and enterprise-SSD sourcing strategy.

memorysupply-riskai-demandsupply-chain
Read more →
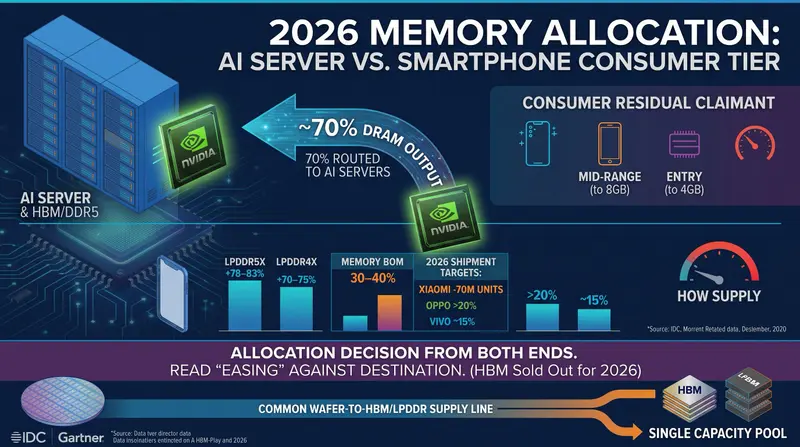
When the Allocation War Reaches the Handset: What the 2026 Mobile-DRAM Squeeze Means for OEM and EMS Sourcing Strategy

August 14, 2026 · By WingCore Editorial

When the Allocation War Reaches the Handset: What the 2026 Mobile-DRAM Squeeze Means for OEM and EMS Sourcing Strategy

The 2026 memory supercycle is usually narrated through HBM and server DDR5, but its sharpest structural consequence is now landing one tier down — in mobile and consumer DRAM. As the big three route roughly 70% of DRAM output to AI servers, LPDDR pricing has repriced violently, memory has become the dominant line in a handset BOM, and OEMs are responding with order cuts and spec downgrades. For sourcing organizations, this reframes consumer-grade memory from a commodity refill into a managed-allocation problem.

memoryai-demandsupply-riskLPDDR4
Read more →
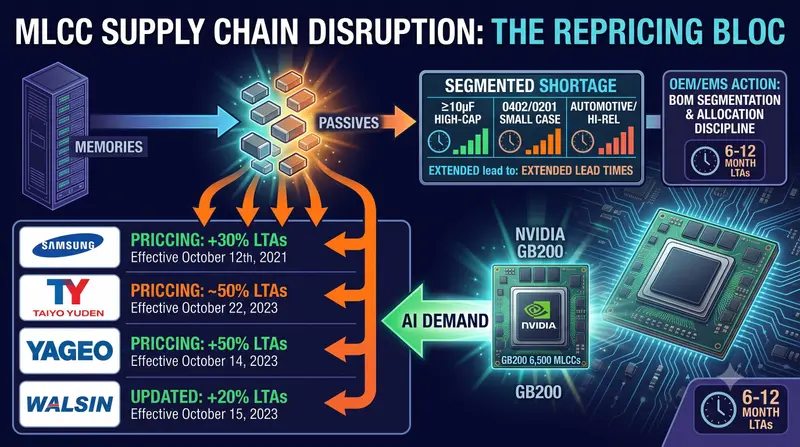
When the Passives Reprice as a Bloc: What the 2026 MLCC Wave Signals for OEM and EMS Sourcing Strategy Beyond the Memory Cycle

August 10, 2026 · By WingCore Editorial

When the Passives Reprice as a Bloc: What the 2026 MLCC Wave Signals for OEM and EMS Sourcing Strategy Beyond the Memory Cycle

The memory super-cycle has absorbed most sourcing attention through 2026, but a parallel and structurally distinct tightening is now underway in multilayer ceramic capacitors. Samsung Electro-Mechanics' portfolio-wide 30% increase took effect August 1, Taiyo Yuden raises from September 1, and book-to-bill ratios across the Japan-Korea leaders have reached five-year highs. This analysis unpacks what a bloc-wide passive repricing means for BOM cost models, allocation posture, and supplier strategy at the OEM and EMS level.

marketprocurementsupply-risksupply-chain
Read more →